If you are searching for information on IIFL gold loan, you are probably thinking about pledging your gold jewellery to get quick cash, or you already have an IIFL gold loan and want to know how to pay it online, use the app, or reach customer care. This article covers all of that in one place — in simple language, without any sales pitch.
I am Shipon, and I write about trading and lending products for everyday Indian readers. My aim here is not to convince you to take a loan from IIFL or anyone else. It is to help you understand how an IIFL gold loan works, what it may cost, and what you should check yourself before signing anything.
Table of Contents
What Is an IIFL Gold Loan?
A gold loan is a secured loan. You pledge your gold jewellery or coins with a lender, and in return, the lender gives you cash based on the value of that gold. IIFL Finance is one of the larger non-banking financial companies (NBFCs) in India offering this product, along with names like Muthoot Finance and Manappuram Finance.
Because the loan is backed by gold, lenders usually process it fast and do not ask for heavy paperwork or a credit score check the way a personal loan does. This is why gold loans are popular for urgent needs — a medical expense, a wedding, a school fee, or working capital for a small business.
How the IIFL Gold Loan Works
- You visit an IIFL Finance branch (or, in some cities, request a home visit) with your gold jewellery and ID/address proof.
- IIFL’s team checks the purity and weight of your gold.
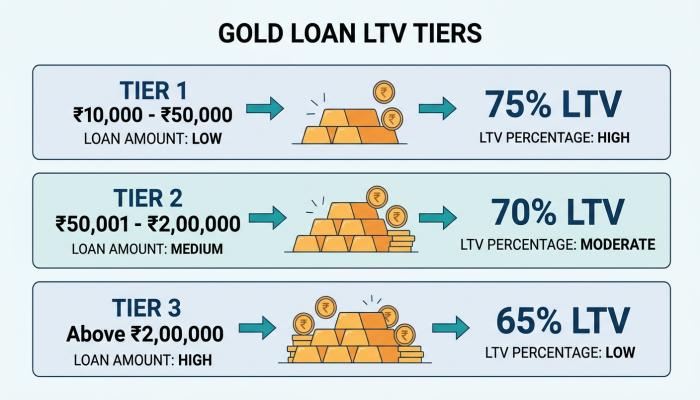
- Based on this valuation and the Loan-to-Value (LTV) rules set by the Reserve Bank of India, IIFL decides how much loan you are eligible for.
- If you accept, the loan is disbursed, often on the same day.
- Your gold stays with IIFL as security until you repay the loan.
Under RBI’s updated norms applicable from 1 April 2026, the maximum LTV for consumption gold loans is capped in tiers — up to 85% for smaller loan amounts, and lower percentages as the loan amount increases. This means the exact percentage of your gold’s value that you can borrow depends on how much you are asking for. Since these rules and IIFL’s own internal policy can be updated, it is best to confirm the current LTV slab directly with IIFL or on their official website before you apply.
IIFL Gold Loan Interest Rate
This is usually the first thing people search for, so let’s be clear about it.
IIFL publishes its gold loan interest rate as starting from around 0.99% per month, which works out to about 11.88% per annum. However, this “starting rate” is generally reserved for larger loan amounts or borrowers who fit a specific risk profile. In practice, many borrowers end up paying somewhere in a wider range, and IIFL itself discloses a broader band that can go up depending on the loan amount, tenure, scheme, and repayment structure you choose.
A few honest points about the interest rate:
- The advertised “starting from” rate is not a guaranteed rate for every borrower. Your actual rate depends on the scheme you are offered at the branch.
- Interest can be charged as simple interest or compounding, depending on the scheme, so ask which one applies to you.
- Rates on gold loans change from time to time based on RBI policy and the lender’s own decisions, so treat any number you read online — including in this article — as indicative, and always confirm the current rate in your official Key Fact Statement (KFS) or sanction letter before signing.
Do not rely only on the headline rate to compare lenders. Ask for the Annual Percentage Rate (APR), which includes interest plus most other charges, since this gives a more realistic picture of your total cost.
Also Read: Stock Analysis: Simple Guide for Indian Investors 2026
Charges Beyond Interest
Apart from interest, gold loans usually involve a few other charges:
- Processing fee — a one-time fee charged at disbursal, which can vary depending on your loan amount and scheme.
- Valuation charges — sometimes bundled with processing, sometimes separate.
- Statutory or documentation charges — for paperwork and compliance.
- Penal or overdue charges — applicable only if you miss payments, and these are usually charged on the overdue amount rather than the full loan.
- Convenience fee on online payments — if you pay through certain third-party billing platforms, a small convenience fee of up to around 2% of the transaction may apply, depending on the payment mode.
The exact numbers for each of these change from scheme to scheme and over time, so don’t take any figure you see quoted online as final. Ask for a written breakup of charges before you take the loan, and read the Key Fact Statement carefully — it is meant to list all charges in one place.
IIFL Gold Loan Payment Online
IIFL allows borrowers to repay their gold loan EMIs or interest dues online rather than visiting a branch every time. Broadly, you have a few ways to do this:
- Through the IIFL Loans mobile app — log in, select your loan account, and use the “Make Payment” option.
- Through IIFL’s website — there is usually a “Pay Now” option for existing loan customers.
- Through third-party bill payment platforms (BBPS) — some payment apps and lending partners let you pay your IIFL gold loan dues through UPI, debit card, credit card, or net banking. A small convenience fee may apply on these routes.
Before paying online, always double-check that you are on IIFL’s official website or app, or a well-known payment platform. Gold loan and other loan repayment scams, where fraudsters send fake payment links, are common in India, so never pay through a link received via SMS or WhatsApp from an unknown number.
IIFL Gold Loan App
The IIFL Loans app is meant to give gold loan (and other IIFL loan) customers a way to manage their account without visiting a branch. Based on IIFL’s own description of the app, it generally lets you:
- View your loan account details and outstanding balance.
- Make loan payments.
- Download your account statement, interest certificate, and loan agreement.
- Apply for a top-up or renewal on an eligible gold loan.
- Raise a service request or complaint ticket.
- Reach customer care directly from the app.
The app can save you a trip to the branch for routine tasks like checking your balance or paying interest. That said, some app reviews mention that certain features — such as making a part-payment toward the principal — have at times required a branch visit instead of being fully available in the app. This kind of feature availability can change with app updates, so if something you need is not showing up in the app, it is worth checking with customer care or the branch directly rather than assuming it is unavailable.
IIFL Gold Loan Quick Pay
“Quick Pay” generally refers to IIFL’s fast, minimal-step online payment option for existing loan customers — where you enter your loan or mobile number and pay the due amount without a full account login. This kind of feature is meant for convenience when you just want to clear an EMI or interest due quickly. Since exact steps and where this option sits on the website or app can change, the safest approach is to look for a “Pay Now” or “Quick Pay” button on IIFL’s official site or app rather than searching for it through a general web search, to avoid landing on an unofficial page.
Common Problems Borrowers Report
Based on publicly available customer reviews and feedback, a few recurring themes come up with IIFL gold loans, as with most gold loan providers:
- Gap between advertised and offered rate. Some borrowers say the rate they were offered at the branch was higher than the advertised starting rate. This is not unique to IIFL — it is common in the industry because the lowest advertised rate is usually for a specific borrower profile or loan size.
- Feature changes in the app. As mentioned above, some users have reported that certain payment options available earlier were later restricted to branch visits.
- Confusion over total repayment amount. Because gold loans can have interest-only periods followed by a lump-sum principal payment (bullet repayment), some borrowers get surprised by the final amount due if they don’t track it during the loan tenure.
None of these are reasons to avoid IIFL specifically — they are reasons to read your loan documents carefully, ask questions before signing, and track your account regularly, regardless of which lender you choose.
Safety of Your Pledged Gold
Lenders like IIFL are required to keep pledged gold in secure, insured storage, typically in bank-grade vaults, until the loan is closed. Ornaments are usually insured against theft or loss while in the lender’s custody. Even so, it is a good practice to:
- Keep photographs of your jewellery before pledging it.
- Note the purity and weight recorded at the time of pledging (this should be on your loan documents).
- Keep your loan account number and documents safe, and track your due dates so your gold does not go to auction due to missed payments.
Who May Find an IIFL Gold Loan Useful
- People who need cash quickly and already own gold jewellery lying idle at home.
- Borrowers who may not qualify easily for an unsecured personal loan due to a limited credit history.
- Small business owners or farmers needing short-term working capital.
Who May Want to Compare Further
- Borrowers who can get a personal loan at a lower or comparable rate without pledging an asset.
- People who are not comfortable with the risk of losing gold to auction if they cannot repay.
- Anyone who has not yet compared the total cost (interest plus charges) across two or three lenders.
Practical Tips Before You Apply
- Ask for the total APR, not just the headline monthly rate.
- Get the processing fee, valuation charge, and penal charge details in writing.
- Understand whether your scheme is EMI-based, interest-only with bullet repayment, or another structure.
- Check the current IIFL gold loan customer care number on IIFL’s official website before calling, since helpline numbers can be updated over time.
- Keep your EMI or interest due dates noted somewhere you will actually see them, such as a calendar reminder.
Frequently Asked Questions
1. What is the current IIFL gold loan interest rate?
IIFL advertises a starting rate of around 0.99% per month (about 11.88% per annum), but your actual rate depends on the loan amount, scheme, and tenure. Always check the latest rate on IIFL’s official website or your sanction letter, since rates can change.
2. Can I pay my IIFL gold loan online?
Yes. You can pay through the IIFL Loans mobile app, IIFL’s official website, or select third-party bill payment platforms that support IIFL loan repayment. Some third-party routes may charge a small convenience fee.
3. What is the IIFL gold loan customer care number?
IIFL’s general customer care number is commonly listed as 1860-267-3000, with an additional number sometimes shown as 7039050000, and email support at socialconnect@iifl.com. Since helpline details can be updated, it is safest to confirm the current number on IIFL’s official website or app.
4. Does the IIFL Loans app let me manage my gold loan fully?
The app allows you to check your balance, make payments, download statements, and apply for top-ups or renewals. Some specific actions, like certain part-payments, may occasionally require a branch visit — this can vary with app updates.
5. What happens if I cannot repay my IIFL gold loan?
If you miss payments beyond the lender’s grace period and notice process, the pledged gold can eventually be auctioned to recover the dues, as is standard for all gold loan lenders in India. It is important to communicate with IIFL early if you are facing repayment difficulty, rather than letting the account go into default silently.
Conclusion
An IIFL gold loan can be a fast and relatively simple way to raise money against gold you already own, and the company offers online payment options and a mobile app to make managing the loan easier. But the “starting” interest rate you see advertised may not be the rate you are actually offered, and charges beyond interest can add to your total cost. The best approach is to ask for a full, written breakdown of the interest rate, charges, and repayment structure before you pledge your gold, and to compare this with at least one other lender.
Disclaimer
This article is for educational and informational purposes only and does not constitute financial advice. Interest rates, charges, and features mentioned here are based on publicly available information and can change over time. Please verify the latest details directly with IIFL Finance’s official website, app, or branch, and consult a qualified financial advisor before making any borrowing decision.